Adaptive Authentication
Authentication That Adapts to The Risk In The Moment.
A correct OTP tells you someone has the code, not who's holding the phone. Bureau reads identity, device, behavioral, and network signals across the whole session and sets the challenge to match the risk. Genuine customers see nothing. A session that turns risky gets challenged before the money moves.


Use cases
One risk decision. Every moment that matters.
Bureau combines identity, device intelligence, behavioral analytics, and network signals into one continuous risk score, then sets authentication to match it. Onboarding, login, transaction, servicing: the same layer decides in real time whether to allow, challenge, or block.


Customer STORIES
Powering Risk Decisions for Global Enterprises




Stay updated with Our resources

Report
.
Sep 1, 2026
Bureau’s Global Fraud Intelligence Report 2026: AI, Identity, and the Future of Fraud
Read more
Ebook
.
Jun 11, 2026
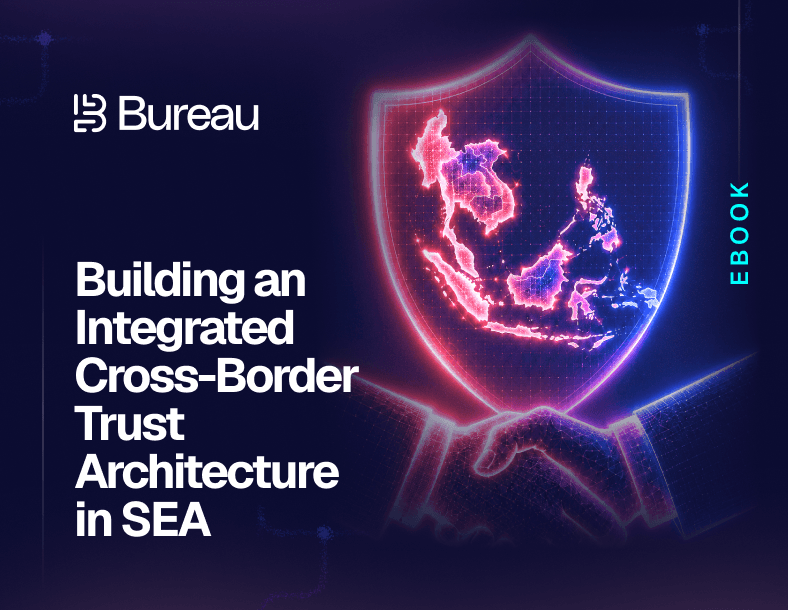
Building an Integrated Cross-Border Trust Architecture in SEA
Read more
Ebook
.
Jun 2, 2026
AI Underwriter: Faster Approvals, Better Fraud Detection
Read more
Ebook
.
May 11, 2026
KYB in Indonesia: Closing Merchant Verification Gaps
Read more
Ebook
.
Apr 30, 2026
Stopping Synthetic Identity Fraud | Bureau
Read more

Ebook
.
Apr 13, 2026
KYB in the Philippines: Closing Merchant Verification Gaps
Read more


frequently asked question
Got questions? We’ve got answers
Is Adaptive Authentication the same as behavioral biometrics?
No. Behavioral analytics is one of several signal families Bureau uses, for anomaly and drift detection rather than as a standalone way to identify a person by how they type or swipe. The risk decision comes from device, behavioral, network, and alternate data combined.
How is this different from transaction monitoring?
Transaction monitoring reacts to a payment after it's initiated. Adaptive Authentication reads the session around it (device, behavior, network) so the decision can happen before the transaction. Where you already run an FRM, transaction data becomes one more input.
Won't more authentication hurt conversion?
Friction appears only when risk rises, so genuine customers get a smoother path than blanket OTP gives them. In deployment, false positives and the unnecessary step-ups that come with them dropped 5–6%.
Which use cases fit best?
Journeys with money movement and a financial exit in a short sequence of events: digital banking, real-time payments cards, wallets, and crypto. That's where re-authenticating on a change in risk catches the takeover before the transfer clears.
Does it help with RBI compliance?
Yes. It implements contextual, device- and behavior-based authentication aligned with RBI's direction on digital-payment security, and equivalent frameworks in other markets, without adding blanket friction.

Follow us on our social
© 2026 Bureau. All Rights Reserved.
SOC 2 Type II Certified • ISO 27001 Certified